

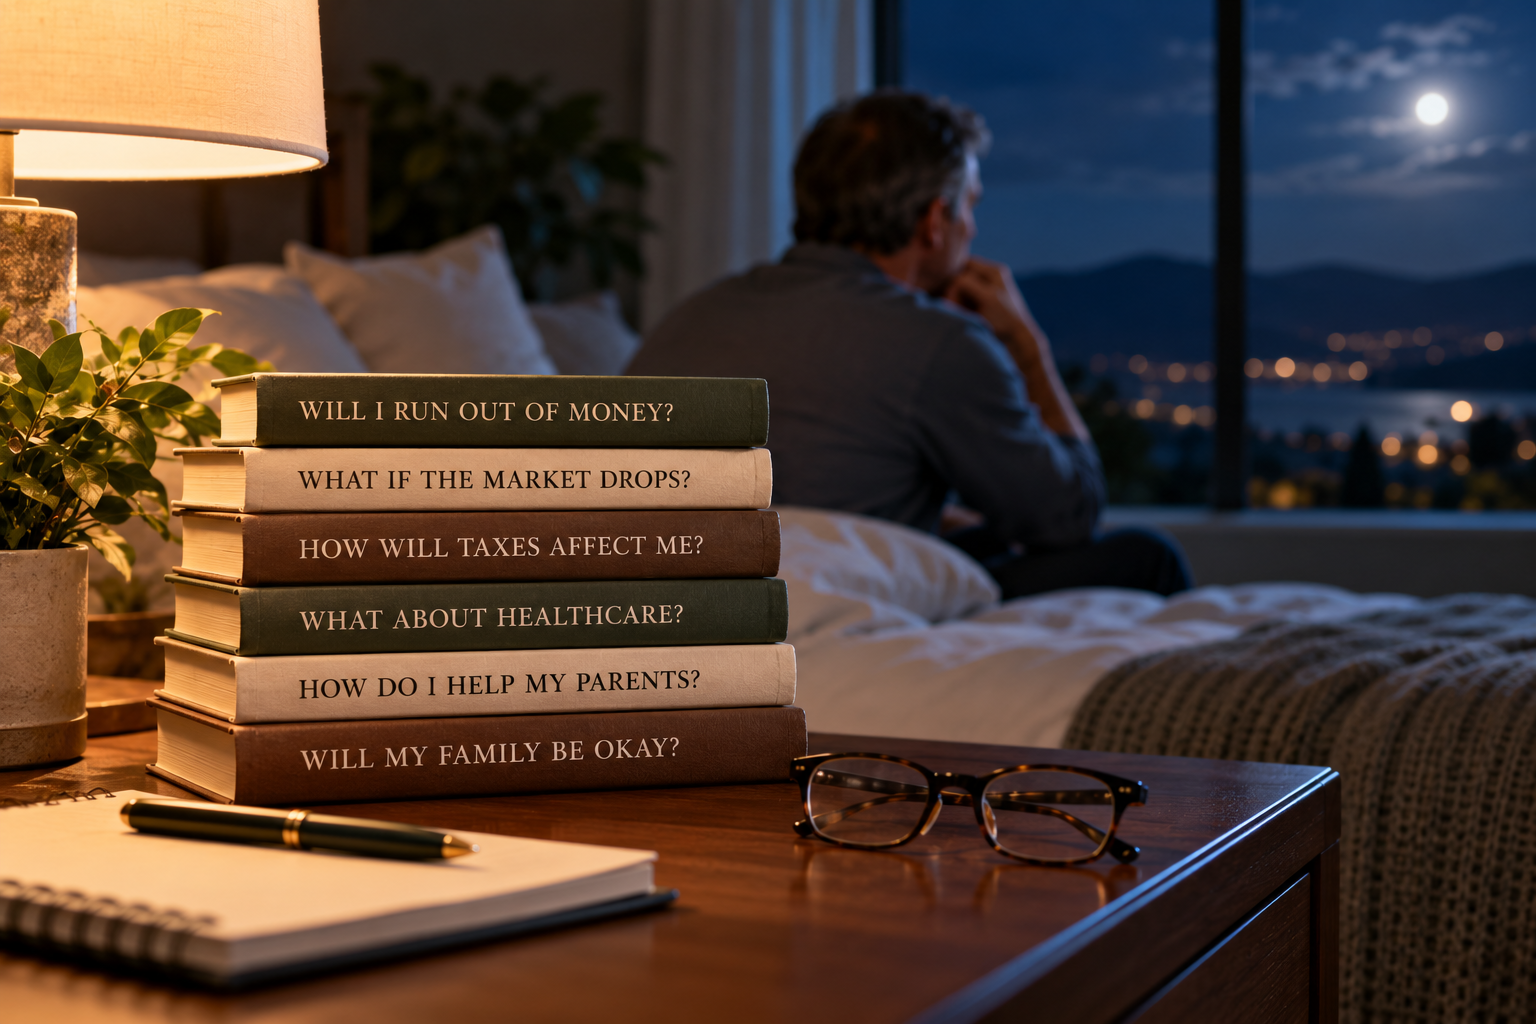
What Financial Concerns Keep You Up at Night?
The Questions Investors Should Be Asking Themselves — Part 4
By Brett Carleton, CFP®, ChFC® President & Founder, Heritage Wealth Management
In the last installment of this series, I asked:
What are you actually trying to accomplish with your wealth?
That's an important question because a financial plan should ultimately help you use your resources to support the life you want to live.
But there's another side to that conversation.
Once we understand what someone wants to accomplish, I also want to understand:
What are you worried could prevent it from happening?
After decades of working with families, I've learned that financial concerns don't necessarily disappear as wealth increases.
They often just change.
Someone early in their career may worry about saving enough.
Someone approaching the next phase of life may worry about running out of money.
A successful business owner may worry about taxes or selling the business.
Parents may worry about their children.
Others may worry about healthcare, aging parents, market declines, or what would happen to their spouse if they weren't around.
And sometimes, a family's greatest financial concern isn't something that shows up on a balance sheet at all.
That's why I think one of the most valuable questions an advisor can ask is simply:
What keeps you up at night?
Having More Money Doesn't Eliminate Financial Worry
It's easy to assume that once someone reaches a certain level of wealth, financial anxiety disappears.
In my experience, that's not necessarily true.
I've worked with families who have accumulated substantial resources and still worry about whether they have enough.
The numbers may show that they're in a very strong financial position. But their concern is still real. That's an important distinction.
A financial plan isn't only about calculating whether something is likely to happen. It's also about understanding why someone is worried about it in the first place.
Perhaps they watched their parents struggle financially.
Maybe they lived through difficult markets and remember seeing their portfolio decline substantially.
Perhaps most of their net worth came from a business or company stock, and diversification feels uncomfortable.
Or maybe they've spent their entire adult life saving and have never learned to feel comfortable spending.
The numbers tell us one part of the story. The person sitting across the table tells us the rest.
“Am I Going to Run Out of Money?”
This is probably one of the most common concerns we hear as people approach the next phase of life.
And it makes sense.
For decades, you've received a paycheck. Then one day, that paycheck may stop. Suddenly, instead of adding money to investment accounts, you may begin withdrawing from them. That psychological transition can be difficult—even for someone who has accumulated significant wealth.
This is where financial planning can be particularly valuable. We can estimate future spending. We can evaluate Social Security, pensions, investment income, and other resources. We can model inflation. We can consider taxes. We can test different market environments and longevity assumptions. The goal isn't to predict exactly what will happen.
We can't.
The goal is to determine whether the plan has enough flexibility to withstand a range of possibilities. Sometimes that analysis identifies something that needs to change. Other times, it tells a family something equally valuable: You may be in better shape than you think.
“What If the Market Drops?”
Market declines create another common source of anxiety.
When markets are doing well, it's relatively easy to say you're a long-term investor.
The harder test comes when account values are falling and the headlines are frightening.
That's when people naturally begin asking:
Should I sell?
Should I move to cash?
Is this time different?
Should we wait until things settle down?
Those reactions are understandable. But financial decisions made during periods of fear can have long-term consequences. That's why we believe the investment portfolio should be connected to the financial plan.
If you know that the money you'll need in the near term isn't dependent on selling stocks during a significant market decline, it may become easier to allow long-term investments the time they need.
We don't build a plan assuming markets will always cooperate.
We build the plan knowing that sometimes they won't.
“What If Taxes Keep Going Up?”
Taxes are another concern we frequently hear, particularly from families who have accumulated significant assets.
Taxes matter.
Good planning may involve decisions around when income is recognized, which accounts are used for spending, charitable giving, Roth conversions, capital gains, estate planning, and other strategies.
But taxes shouldn't become the only consideration.
I've seen people become so focused on avoiding taxes that they lose sight of the larger financial objective.
Sometimes paying a tax today may create greater flexibility tomorrow.
Sometimes the lowest-tax decision isn't necessarily the best overall financial decision.
The question shouldn't always be:
“How do I pay the least possible tax this year?”
A better question may be:
“How do taxes fit into my overall financial plan over time?”
“What If My Health Changes?”
Some financial concerns are difficult because they involve things we can't control.
Health is one of them.
As we age, planning increasingly involves questions about healthcare, long-term care, housing, and who may help us if we can no longer manage everything ourselves.
Those conversations aren't always comfortable.
But avoiding them doesn't reduce the risk.
Planning can mean evaluating insurance.
It can mean making sure estate documents are current.
It can mean discussing where you would want to live if your health changed.
It can mean making sure your children know who your advisors are and where important information can be found.
And it can mean thinking about how much financial flexibility you want available if circumstances change.
We can't plan away every uncertainty. But we can prepare for many of them.
“What About My Parents?”
For many families, financial planning isn't limited to their own household.
As parents live longer, adult children may find themselves helping with healthcare decisions, housing transitions, finances, or caregiving.
Sometimes that responsibility arrives gradually. Other times, it happens almost overnight. I've experienced these transitions in my own family, and they've reinforced something I believe strongly:
Planning ahead is much easier than planning during a crisis.
If your parents are getting older, it may be worth having conversations before they're urgently needed.
Do you understand their wishes?
Are their estate documents current?
Who has financial and medical powers of attorney?
Where are important records kept?
What type of care could they afford?
Who would help make decisions?
These aren't simply financial questions. They're family questions with financial consequences.
“Will My Family Be Okay Without Me?”
For some people, this is the concern underneath almost everything else.
If something happened to you tomorrow, would your spouse understand the financial picture?
Would they know who to call?
Are beneficiary designations current?
Are your estate documents in order?
Is there enough liquidity?
Does your spouse understand your investments—or have you always handled everything?
Are there children or other family members who will need ongoing support?
For families with a loved one who has special needs, these questions can become even more important because planning may need to extend far beyond the parents' lifetimes.
These conversations can be difficult. But they are also an important expression of caring for the people who matter to us.
Some Concerns Require Action. Others Require Perspective.
One of the valuable things about putting a financial concern into words is that we can begin doing something with it.
Sometimes the answer is action.
Maybe your estate plan needs updating.
Maybe you're taking more investment risk than necessary.
Maybe you need additional cash reserves.
Maybe insurance needs to be reviewed.
Maybe your spending assumptions need to change.
But sometimes the answer isn't another financial product or strategy. Sometimes it's perspective.
If someone tells me: “I'm afraid I'm going to run out of money,” and our planning shows that they could withstand difficult markets, higher spending, unexpected expenses, and a long life without exhausting their resources, the solution may not be accumulating another million dollars.
The solution may be helping them develop enough confidence in their plan to start enjoying what they've already built.
That's an important part of financial planning too.
Put Your Biggest Concern Into One Sentence
Here's an exercise I think can be useful.
Finish this sentence:
The financial issue I worry about most is…
Don't worry about whether the concern sounds rational.
Just answer it.
Maybe it's:
Running out of money.
Another major market decline.
Paying too much in taxes.
My spouse being financially secure.
My parents needing care.
My children making poor financial decisions.
My own health.
Having enough to care for a family member with special needs.
Not knowing whom to trust.
Once you've identified the concern, ask a second question:
What would need to be true for me to feel more confident about it?
That question begins moving you from worry toward planning.
A Good Financial Plan Should Help You Sleep Better
No financial plan can eliminate uncertainty.
Markets will surprise us.
Tax laws will change.
Families will change.
Our health will change.
Life will happen.
The goal isn't to create a plan in which nothing ever goes wrong.
I think the goal is to build a plan that's strong enough and flexible enough that when something does go wrong, you don't have to abandon everything you're trying to accomplish.
So ask yourself:
What financial concern keeps me up at night?
Then don't stop there.
Ask whether you've actually built a plan around it.
Because sometimes the greatest value of planning isn't finding another way to accumulate more.
It's having greater confidence that the people and priorities you care about are prepared for whatever comes next.
Coming Next: What Did the Last Market Decline Teach You About Yourself? In Part 5 of The Questions Investors Should Be Asking Themselves, we'll turn specifically to investor behavior. It's easy to describe yourself as a long-term investor when markets are rising. What matters more is what you actually do when they're falling. We'll explore what your reactions during previous market declines can teach you about risk, your investment strategy, and whether your portfolio truly fits your financial plan.
About This Series The Questions Investors Should Be Asking Themselves is an ongoing Heritage Wealth Management series exploring questions that can lead to more meaningful financial planning conversations. Because sometimes improving your financial life doesn't begin with finding a better answer. It begins with asking a better question.
Disclosure: This material is for informational purposes only and should not be considered investment, tax, or legal advice. Investment strategies involve risk, including possible loss of principal. The questions and concepts discussed in this article were inspired in part by the work and perspectives of David Booth, founder of Dimensional Fund Advisors and author of Stay Calm. Heritage Wealth Management is not affiliated with or endorsed by David Booth or Dimensional Fund Advisors.